Add AD Mortgage as your preferred source on Google
Correspondent lending is a model where a lender originates and funds new loans in its own name and then sells them to investors. In some cases, a correspondent lender also underwrites the files, but in others it doesn’t – we’ll discuss the difference in detail. The borrower works with that company from application through closing.
For a mortgage business, the model sits between brokering every file to a wholesale lender and running a fully independent mortgage bank, with more control than the first one and less balance sheet than the second.
Understanding how the correspondent channel works matters if you’re a broker or mortgage company owner weighing whether the added control and margin are worth the added responsibility before you commit capital and staff to the switch.
From this article, you will learn:
What correspondent mortgage lending is and what a correspondent loan involves, compared with brokering and wholesale lending.
Who correspondent investors are, and how selling into the secondary market lets a company fund more loans.
The step-by-step loan process: origination, underwriting, closing, funding, and the loan sale.
The difference between delegated, non-delegated, and mini-correspondent lending.
What correspondent lending adds to a mortgage business and what it asks for in return.
What to look for in an investor partner, from pricing to underwriting support to how exceptions get resolved.
Who holds servicing rights after a correspondent loan is sold.
Whether moving from broker to correspondent fits your company now, whether you’re a new shop or an established one, and what it takes to get there.
Not partnering with AD Mortgage yet? Now is the time! Fill in the Correspondent Package to submit your documents and start the approval process.
To understand correspondent lending, it helps to start with three core players: the correspondent lender (or seller), the correspondent investor (or purchaser), and the secondary mortgage market they connect to.
What is a Correspondent Lender?
It’s a company approved by one or more investors to originate and close loans with its own funds, under its own name, and then deliver those loans to investors for purchase.
Who is the Investor?
The correspondent investor (also called the purchaser) is the company that buys the closed loan from the correspondent lender. This can be a wholesale lender like AD Mortgage, a national bank, a credit union, a portfolio lender, or a government-sponsored enterprise such as Fannie Mae or Freddie Mac – any entity approved to purchase loans in the secondary market.
Before any loan closes and changes hands, the investor sets the underwriting guidelines and investor requirements the correspondent lender must follow – pricing, eligibility, and documentation requirements all flow from this relationship.
How the Secondary Market Helps Correspondent Mortgage Lending
Selling into the secondary mortgage market returns capital that would otherwise sit tied up in a single correspondent loan. It allows the company to fund the next one.
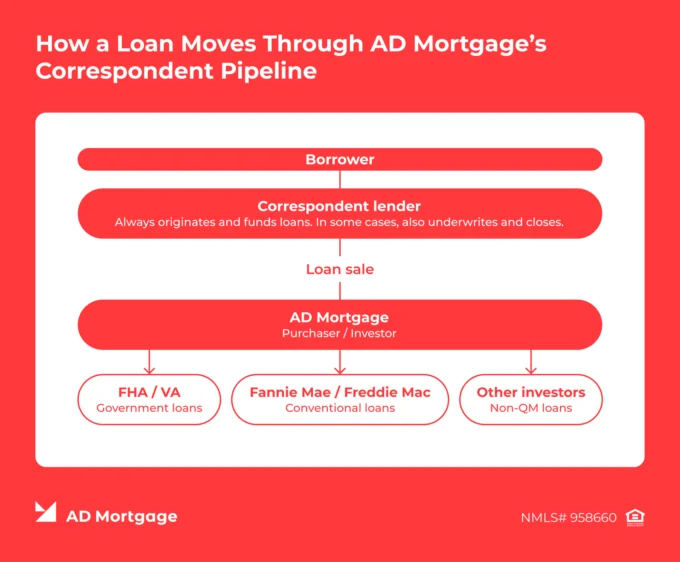
For AD Mortgage, that means reselling purchased loans to its own network of investors: Fannie Mae and Freddie Mac for conventional loans, Federal Housing Administration (FHA) and U.S. Department of Veterans Affairs (VA) for government loans, and other third-party investors for Non-QM loans. This liquidity cycle plays out at enormous scale across the industry – Fannie Mae alone acquired $408 billion in single-family loans during 2025.
Most correspondent lenders fund through a warehouse line of credit and repay the draw when the investor purchases, though warehouse financing is not the only route. Well-capitalized firms can also lend from their own cash.
How Does Correspondent Lending Work?
Let’s briefly cover the steps a correspondent lender takes to move the file through the pipeline.
1. Loan Origination
The loan process begins with the correspondent lender taking the application, building the borrower relationship, collecting documentation, and selecting the product and investor the file will eventually go to. At the loan origination stage, a correspondent lender functions much like a retail lender – works directly with the borrowers. Product selection carries more weight than for a mortgage broker, since the loan must go to an investor that has approved both the correspondent lender and the loan program.
2. Underwriting
It depends on the type of the correspondent lender: delegated or non-delegated. We discuss the difference in the Types of Correspondent Lending section. In short, delegated lenders do in-house underwriting, while non-delegated send files to investors for that.
‘For investors like AD Mortgage, there’s usually no real difference in the underwriting process. We evaluate every file with the same level of accuracy, regardless of the channel it comes from, whether Wholesale or Correspondent,’ – shares Anastassiya Materova, Senior Underwriter at AD Mortgage.
‘Sometimes correspondent lenders submit everything combined into one large PDF, sometimes hundreds of pages long. That’s certainly not a mistake, but having documents uploaded separately can make it easier for the underwriters to review the file efficiently and help keep the process moving smoothly. We really appreciate our correspondent partners who take the extra step to organize and upload their files separately. It helps us provide the best possible experience for everyone involved.‘
3. Closing
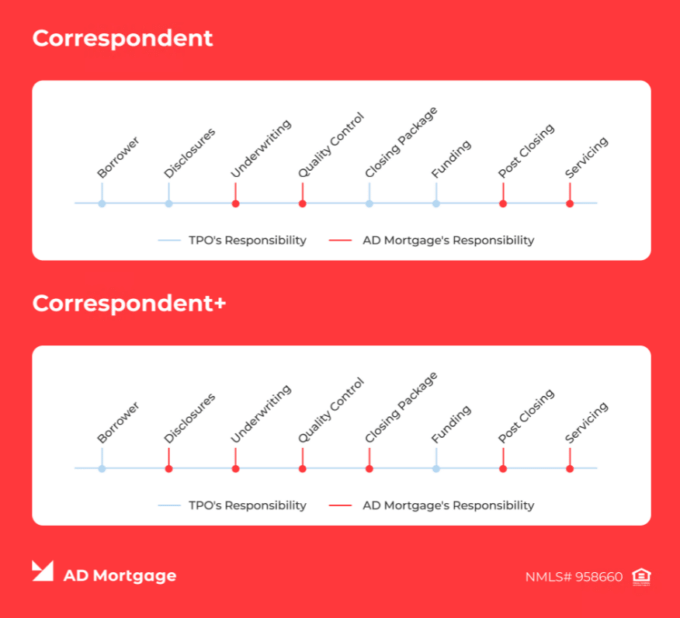
‘Who puts together the Closing Package depends on the channel – Correspondent or Correspondent+ (two service tiers, detailed below). At AD Mortgage, we handle it for our Correspondent+ partners,’ –explains Anna Kovan, Closing Manager at AD Mortgage.‘Ahead of that, we verify third-party fees, ensure TRID compliance, clear closing conditions, and issue the closing documents.’
At the closing stage, the correspondent lender usually prepares the closing package and ensures everything is compliant and ready for the consumer to sign. In the mini-correspondent model (called Correspondent+ at AD Mortgage), the investor prepares it instead.
4. Funding
Funding is the correspondent lender’s responsibility. On the closing date, the correspondent mortgage lender sends funds to the title or escrow company, which distributes them: payment to the seller (for a purchase) or payoff of existing liens (for a refinance), plus closing costs and other disbursements. The loan closes in the correspondent lender’s own name. After that, the preparation for the loan sale begins.
5. Loan Sale
The correspondent lender delivers the closed loan file to the investor, who reviews it against the guidelines, clears purchase conditions, and buys the loan.
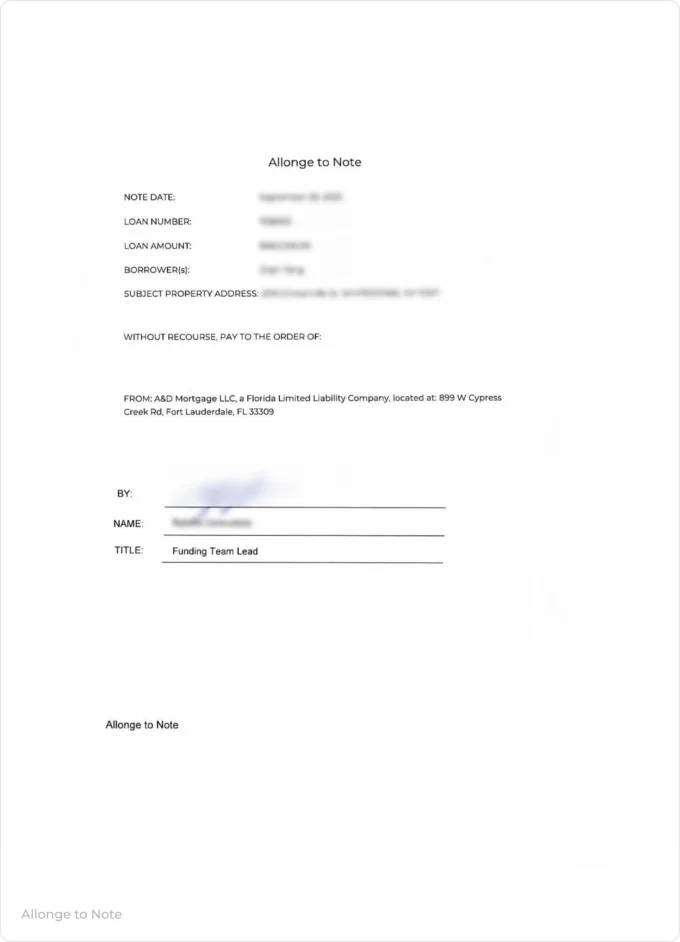
Before AD Mortgage purchases a loan, it issues a Purchase Advice (PA) – confirmation that the loan has been accepted for purchase. But before we issue the PA, we must receive the complete collateral document package, including the Note, any applicable Addendums to the Note, the Allonge to the Note, and the Bailee Letter. Once the original collateral package has been delivered to our office, we will issue the PA and proceed with funding.
Sample Allonge to Note document, one of the required collateral documents in a correspondent loan sale.
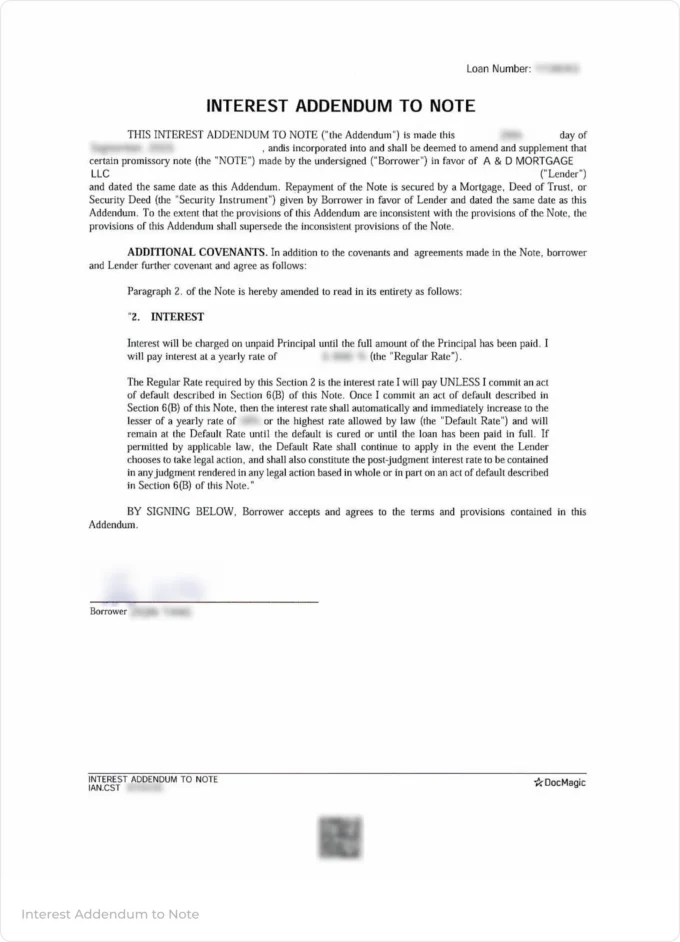
‘To speed up the process, we recommend that partners carefully double-check the collateral document package before sending it over. Some important pages get missed from time to time – most often the Addendum to Note (where applicable), which is also part of the Note. When that happens, one of our specialists reaches out to the partner and lets them know what still needs to be uploaded.’– shares Natalia Cerevataia, Funding Team Lead at AD Mortgage.
Sample Interest Addendum to Note document, an example of an Addendum to Note required in the collateral document package.
6. Servicing
Some correspondent lenders sell their loans servicing-released, meaning the buyer takes over payment collection and the borrower relationship. Servicing-retained deals keep that relationship and the servicing income, but require servicing infrastructure and more capital.
If you’re just getting started as a correspondent lender with AD Mortgage, check out our Correspondent Loan Submission Checklist – it will help you reach CTC faster.
Correspondent relationships come in three common shapes, separated by how much underwriting authority the investor hands over and how much infrastructure the correspondent needs to hold.
Delegated Lending
The delegated correspondent lender has the authority to underwrite the loan themselves, without sending files out for a pre-close decision. From one perspective, that suggests greater control over the process. From another, it also means owning the quality control burden, absorbing the cost of an underwriting error, and answering for loans the investor later may find defective (if any).
Non-Delegated Lending
The investor underwrites or controls the credit decision before the loan closes, but the correspondent lender still closes and funds in its own name. Underwriting risk is lower, but so is the process control.
Mini-Correspondent Lending
This is a transitional structure for companies moving from brokerage toward correspondent operations. Requirements are lighter and volume commitments are typically smaller than for a full delegated correspondent, though specifics vary by investor agreement. The company still closes loans in its own name – the same as any correspondent lender – but takes on that responsibility at a smaller scale before building out full underwriting infrastructure.
For a mortgage broker testing whether the model fits, this can lower the cost of finding out, provided the compliance and quality-control obligations that come with closing loans are treated as real from day one.
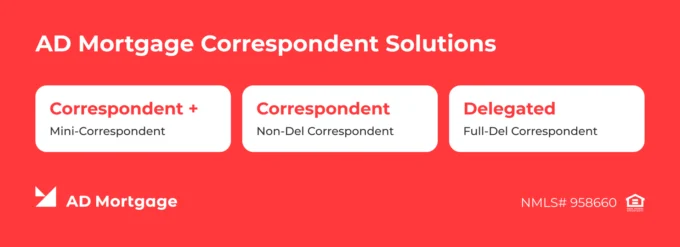
At AD Mortgage, we have specific names for each type of correspondent lending.
Correspondent Lending vs Wholesale Lending vs Mortgage Brokerage
These three models differ on whose money closes the loan and whose name the borrower sees. A mortgage broker submits files to a wholesale lender that underwrites and funds them. In wholesale lending, the lender supplies capital and underwriting while the mortgage broker keeps the borrower relationship. A correspondent does both jobs – originates and funds – then sells the result.
Feature
Mortgage Broker
Wholesale Lender
Correspondent Lender
Works directly with borrower
Yes
No
Yes
Funds loans in own name
No
Typically funds broker-originated loans
Yes
Controls underwriting
No
Yes
Depends on delegated / non-delegated status
Uses warehouse or own capital
No
Yes
Yes
Sells loans to investors
Not applicable
Often
Yes
Borrower-facing brand
Broker
Broker
Correspondent
Operational responsibility
Lower
Higher
Higher
Control, economics, and responsibility move together:
Brokers carry the least operational weight and own the least of the transaction, which is why brokering is the lowest-cost way to originate.
Wholesale lenders supply the capital and the credit decision but stay invisible to the borrower.
Correspondents take on the most of both, including the borrower-facing brand: referral partners remember whose name closed the loan.
Benefits and Risks of Correspondent Lending for Mortgage Businesses
Potential Benefits
Closing in your own name changes how consumers and referral partners see the company, as the brand on the note is yours. You control the closing calendar instead of waiting in a queue. Correspondents capture origination economics plus any gain on the loan sale, rather than a single mortgage broker compensation figure.
Investor relationships widen product access, including Non-QM loan programs. Selling to more than one investor also lets you deliver each loan to the best available bid instead of accepting a single rate sheet. Over time, consistent execution under your own brand builds a lending business with enterprise value rather than a referral pipeline.
Potential Challenges
Every benefit comes with an obligation:
Warehouse lines require covenants, audited financials, and ongoing liquidity management.
Investors review eligibility continuously, not just at approval.
There is a repurchase risk: a loan deemed defective can come back to you.
Capital stays committed from funding until purchase, so liquidity needs active management, especially when investor turn times slow.
Underwriting, QC, and post-closing staff all cost money before they produce revenue.
When Does Moving From Broker to Correspondent Make Sense?
The move favors companies that already have the pieces in place: consistent production volume, operational infrastructure, experienced underwriting and post-closing staff, documented compliance and QC processes, and warehouse financing access. One factor isn’t a capability but an appetite – enough desire for control over closing and the client experience to take on what comes with it.
‘Moving from broker to correspondent makes sense when a shop has steady volume, a warehouse line in place or on the way, and the team to support it,’ says Brennen Moloney, SVP Business Development at AD Mortgage.
Capital is the hard gate. Fannie Mae requires approved sellers and servicers to maintain an Adjusted Net Worth of at least $2.5 million, plus an amount tied to servicing portfolio size. Investors set their own thresholds on top of that, and applications typically require audited financials, MERS approval, insurance and fidelity bonds, written compliance policies, and agency approvals where applicable.
‘The payoff is more margin on every loan, more control over the process, and your own name on the closing documents, so the borrower relationship stays with you,’ Brennen adds.‘The tradeoff is responsibility: as the lender of record, you’re funding the loan and taking on more compliance and repurchase risk.’
How Can Correspondent Lender Choose a Lending Partner?
Start with structure: does the investor offer delegated, non-delegated, and mini-correspondent options, so you can grow into the relationship over time? Then check product breadth.
From there, it comes down to the day-to-day stuff. Ask about pricing and how often it updates, underwriting support when a file gets complicated, purchase turn times, how fast post-closing and purchase advice move, what the delivery and tracking tech looks like, and how clear the guidelines are. Also, ask who you call when something stalls, and whether that person knows your pipeline.
One of the main questions to ask: how does the investor handle the stuff that doesn’t fit the usual boxes? A long guideline list doesn’t mean much if exceptions take forever to get resolved.
Is Correspondent Lending Right for Your Mortgage Business?
Correspondent lending offers control over closing, brand, and margin, but it asks for more operational and financial responsibility in return.
AD Mortgage runs mini, non-delegated, and fully delegated channels across 49 states, backed by 24-hour underwriting. If your volume, staffing, and capital support it, explore our correspondent lending solutions or start the Correspondent Package to become AD Mortgage’s approved Correspondent Lender.
FAQ: Correspondent Lending
Do correspondent lenders use their own money?
Yes, though ‘own money’ usually means a warehouse line rather than cash on hand. The correspondent draws on that line at closing, then repays it once the investor purchases. Firms with enough capital fund from their own resources instead.
What is the difference between delegated and non-delegated correspondent lending?
Delegated correspondents hold underwriting authority and approve loans against investor guidelines themselves, gaining speed and control while owning the quality control risk. Non-delegated correspondents send files to the investor for the credit decision before closing, which cuts underwriting risk and process control together.
Can a mortgage broker become a correspondent lender?
Yes. For a mortgage broker, it requires state licensing for the lending activity, minimum net worth and capital, warehouse financing, underwriting and post-closing staff, documented compliance and QC processes, and approval from each investor you sell to. Many start as mini-correspondents to build the infrastructure gradually.
What happens after a correspondent lender sells a loan?
Ownership transfers to the investor, who holds the loan or pools it into a security. Servicing is a separate question: on a servicing-released sale the borrower starts paying the new servicer, while a servicing-retained correspondent keeps collecting payments and stays the client’s point of contact.