Add AD Mortgage as your preferred source on Google
Whether you originate loans as an independent broker or fund them as a correspondent, you operate in the world of third-party origination (TPO). But while the acronym is simple, the underlying mechanics of the mortgage process are not. TPO models differ in who underwrites the file, who controls the funding, and whose name appears on the final mortgage note.
From this article, you will learn:
What third-party origination is, and how the TPO mortgage meaning traces back to Fannie Mae’s own definition
How a mortgage broker and a correspondent lender each move a mortgage loan through the mortgage origination process, compared to a retail lender
Who handles underwriting for different channels
How delegated and non-delegated correspondents close and fund a mortgage loan before it moves through the secondary market
What benefits and responsibilities come with third-party lending
This article is for independent brokers and correspondent lenders who want to understand how the wholesale and correspondent channels differ and choose the right TPO partnership for their business.
What is a Third-Party Originator in Mortgage Lending?
The mortgage industry has its own shorthand for this setup, which starts with a formal definition.
Fannie Mae’s Definition
Fannie Mae’s Selling Guide puts it as follows: ‘A third-party origination is any loan that is completely or partially originated, processed, underwritten, packaged, funded, or closed by an entity other than the seller (or its parent company, controlled affiliate or subsidiary)… This includes mortgage brokers or correspondents, which are known as third-party originators.‘
What Does TPO Stand for in Mortgage?
In plain terms, third-party originators (TPOs) play a vital role as the bridge between borrowers and mortgage lenders. The ‘originator’ part of the name means they originate loans: they submit the file and guide the borrower through the process through closing.
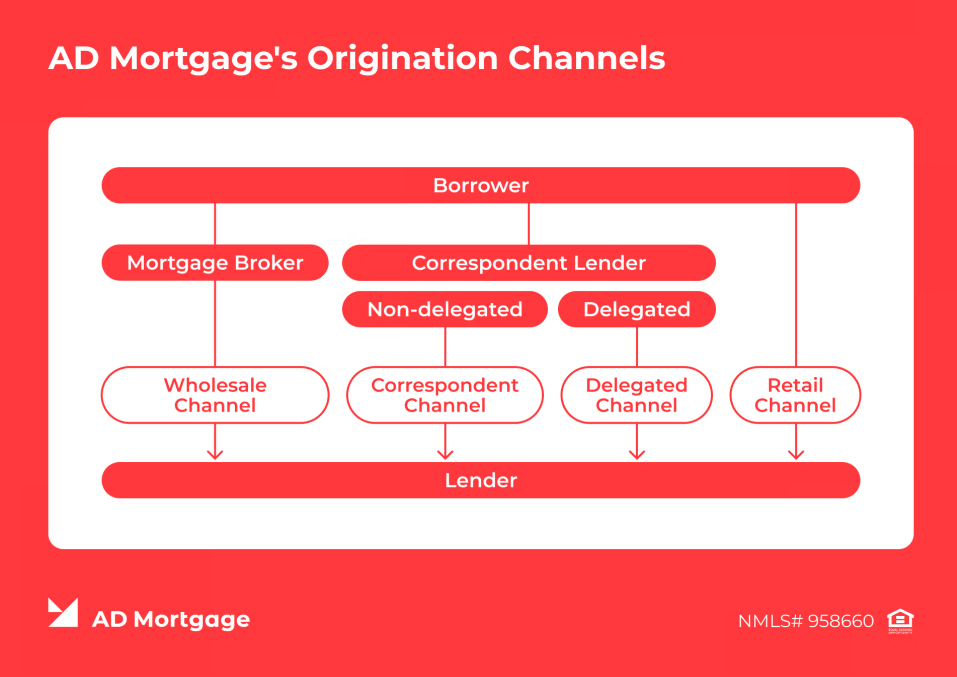
TPOs work with lenders through specific channels. The mortgage industry runs on three of them – wholesale, correspondent, and retail – but a TPO only works through the first two. Which one a given company uses comes down to the structure of its lending partnership.
Types of Third-Party Originators
Both wholesale and correspondent partners count as TPOs, though each company plays a different role day to day.
Mortgage Brokers → Wholesale Channel
A broker takes the loan application, gathers borrower information, and sends the file to a wholesale lender, which underwrites and funds it. The broker never closes in its own name and carries no warehouse line.
Their job is connecting borrowers with financing: matching them to the right loan products and finding a path through complex or unusual scenarios. Brokers and their loan officers license through NMLS under the SAFE Act, and the rules around that license vary by state.
Correspondent Lenders → Correspondent Channel
Correspondent lenders fall into two categories under one umbrella: delegated and non-delegated.
Delegated Lenders
Delegated lenders handle the entire process in-house – originating, underwriting, closing, and funding the loan in their own name. Once it closes, they deliver the file to an investor (AD Mortgage, for example), which reviews the loan and purchases it.
Non-Delegated Lenders
Non-delegated lenders originate and close loans under their own name too and fund them using their own warehouse line. But they don’t hold the underwriting process: the file goes to a partner, like AD Mortgage, for underwriting before closing*. The correspondent lender then sells the funded loan to that partner.
‘AD Mortgage structures its own channels a little differently. The Correspondent Channel here serves non-delegated partners specifically (what the industry broadly calls Non-Del), while delegated partners work through their own dedicated channel.‘ – shares Brennen Moloney, SVP Business Development at AD Mortgage.
Mortgage Broker vs Correspondent Lender vs Retail Lender
What is the Retail Channel?
Retail is worth a quick detour before the comparison, since it’s the baseline the other two channels differ from. The retail channel is a direct line between mortgage lenders and consumers, without an intermediary, which is the exact opposite of third-party origination.
‘A single NMLS-licensed company can run both sides at once: a retail lender when it works directly with a customer to originate and fund a home loan, and a wholesale lender if it also maintains a channel for independent brokers.’– explains AD Mortgage Compliance Team, – ‘but it depends on the company’s license type and the state it operates in.’
When placed side by side, the three look like this:
Mortgage Broker
Correspondent Lender
Retail Lender
Works directly with the customer
Yes
Yes
Yes
Underwrites the file
No – the wholesale lender does
Depends on delegated / non-delegated status
Yes
Funds and closes in its own name
No
Yes
Yes
Sells the loan after closing
Not applicable
Yes
Yes
Counts as a TPO
Yes
Yes
No
How Does Third-Party Origination Work?
The process breaks into five steps, and most of them split by channel partway through.
Step 1: Loan Application and Documentation
The originator takes the client’s mortgage application, helps fill in the missing borrower information (including the loan amount and property details), pulls credit reports, and assembles income and asset records. For loans subject to TRID, the lender must deliver or mail a Loan Estimate disclosing the loan origination fees and other upfront costs, within three business days of a complete application (AD Mortgage also applies this to loans not regulated by TRID).
Step 2: Lender and Program Selection
A broker shops its approved wholesale lenders. A correspondent picks among its investors instead.
Step 3: Underwriting
Here the process splits by channel. On broker files, the wholesale lender underwrites. A delegated correspondent underwrites its own file, and a non-delegated correspondent sends it to the investor first.
Step 4: Closing and Funding
On broker files, the wholesale lender funds and closes in its own name. The correspondent draws on its warehouse line and closes in their own name.
Step 5: Loan Sale
The correspondent delivers the closed loan to its investor. The broker’s file already belonged to the wholesale lender from the start.
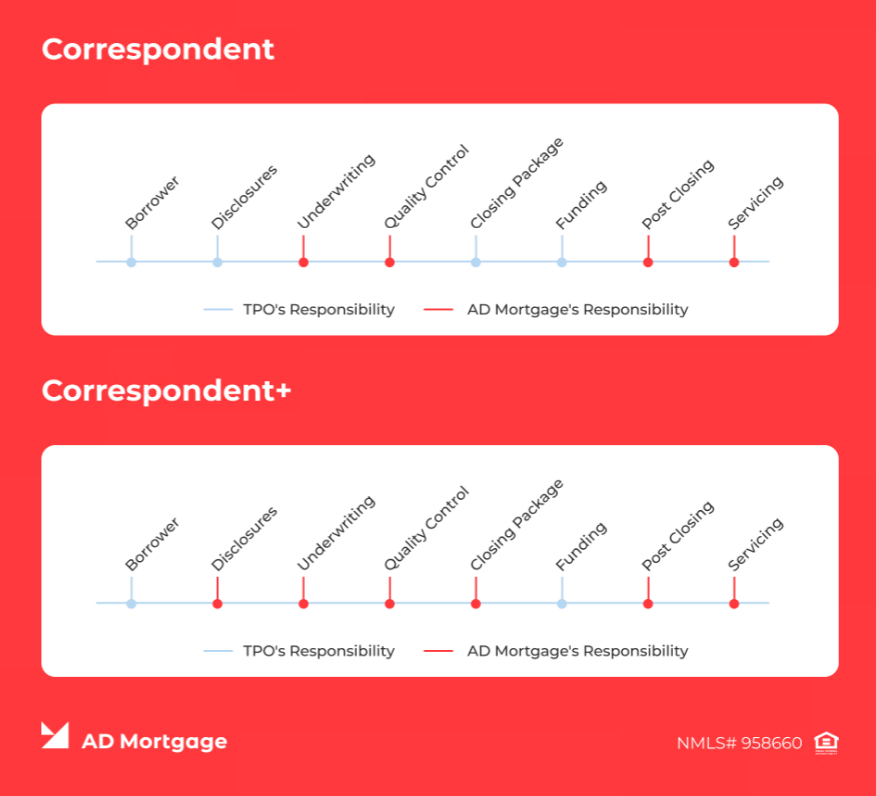
‘AD Mortgage offers two options for correspondent partners here: Correspondent and Correspondent+. Correspondent partners handle disclosures and the closing package themselves, and Correspondent+ hands both over to AD Mortgage.’– clarifies Epiphany Tymes, Disclosure Specialist at AD Mortgage.
Let’s Discuss an Example
Picture a property buyer with three rentals and no W-2 income. Through a broker, the wholesale lender underwrites and funds the loan, and that lender’s name shows up at closing. Through a delegated correspondent, the same borrower closes on the correspondent’s note instead, and the loan changes hands only afterward.
Have a scenario like this one, or something different? Send us the details, and an AE will reach out quickly to help match it with the right program.
As a TPO, you are the sales engine for wholesale lenders. You bring them access to local markets without the overhead of a branch, and borrowers receive a seamless experience with someone who already knows where a loan will clear underwriting.
Guidelines vary across the roughly 4,800 institutions – banks, credit unions, and non-bank lenders alike – that report mortgage data under HMDA. Retail banks, in most cases, stick to conventional and government-backed programs, so a 1099 earner or an ITIN borrower can struggle to find a fit there. Working with multiple investors lets an originator compare loan options across several programs, which is an advantage over relying on just one lender.
What It Takes to Succeed as a TPO
Investors hold TPOs to strict standards: Fannie Mae, for one, requires lenders to review each TPO’s loan performance every quarter, tracking delinquencies and foreclosures. TPO origination brings broad market access and full control over client relationships, though it doesn’t promise a lower rate or a faster closing.
Explore Partnership Options with AD Mortgage
AD Mortgage serves both mortgage brokers and correspondent lenders with Non-QM, DSCR, bank statement, ITIN programs, and more, available across 49 states and 24-hour underwriting turn times. More than 9,000 brokerage companies already partner with us. Explore your partnership options and find the structure that fits your business.
No. Every mortgage broker is a TPO, but not every TPO is a broker. Correspondent lenders are third-party originators too, and they underwrite, close, and fund in their own names before selling the loan. TPO is the category, broker and correspondent are two channels inside it, separated by whichever company holds the funding and the underwriting authority.
Do Third-Party Originators Fund Loans?
That depends on the channel. Brokers do not: the wholesale lender funds and closes the loan, and its name appears on the note. Correspondents do fund (as third-party mortgage lenders),usually drawing on a warehouse line, then sell the closed loan to an investor to replenish that line. Both qualify as third-party originators despite the difference.
Who Underwrites a TPO Mortgage?
On broker files, the wholesale lender underwrites. On correspondent files, the agreement decides: a delegated correspondent underwrites to investor guidelines and owns the resulting underwriting costs and quality control duties, while a non-delegated correspondent submits the file to the investor for underwriting before the loan closes.
*In this context, closing does not mean closing through AD Mortgage.