Post content:
Add AD Mortgage as your preferred source on Google
North Carolina is a diverse housing market – and no single place or loan program is ‘best’ for the entire state. A buyer eyeing a cottage on the Outer Banks, a young family comparing suburbs around Raleigh, and a first-timer hunting for an affordable starter home in Bertie County are all shopping in North Carolina. However, their approaches and experience will be entirely different.
Coastal buyers may stretch their budgets for salt air and sound views. Buyers around the Triangle and Charlotte tend to weigh career opportunities, schools, and commute times, while those in the rural northeast are often looking first for a payment that leaves room in the monthly budget.
Also, North Carolina ranks third for real estate investment opportunities, according to AD Mortgage’s recent US Real Estate Investment Opportunities by State Report.
AD Mortgage did a deep dive into the North Carolina housing market, spoke to experts in the state, and identified some of the best places to buy a home in North Carolina in 2026.
AD Mortgage has 20 years of experience in the mortgage industry providing mortgage solutions, technology, and support for broker partners. Become a Partner to work with a lender focused on helping you close.
Close Look at the North Carolina Housing Market
Averages hide a lot in a state this varied. For example, Zillow estimates North Carolina’s typical home value at $334,773. At the same time, typical home values run from roughly $600,000 in Dare County to about $65,000 in Bertie County – a gap of nearly tenfold within one state.
We reviewed multiple factors and numbers behind the state’s markets to spotlight the North Carolina locations worth a closer look in 2027.
Full research is available in the downloadable North Carolina Homebuyers Guide PDF. The analysis includes:
- Typical Home Values
- Homebuying Entry Costs and Estimated Down Payments
- Property Taxes and Insurance
- Median Household Incomes
- Location
- Down Payment Assistance (DPA) Programs
Our selection of the most prominent North Carolina locations to buy a home is not definitive. It can serve as a strong starting point for buyers searching for a property and for mortgage professionals helping borrowers in their journey.

Our research is based on publicly available housing and economic data, along with local market insights and affordability trends. Note that down payment assistance details are subject to current funding, eligibility requirements, lender requirements, and program changes.
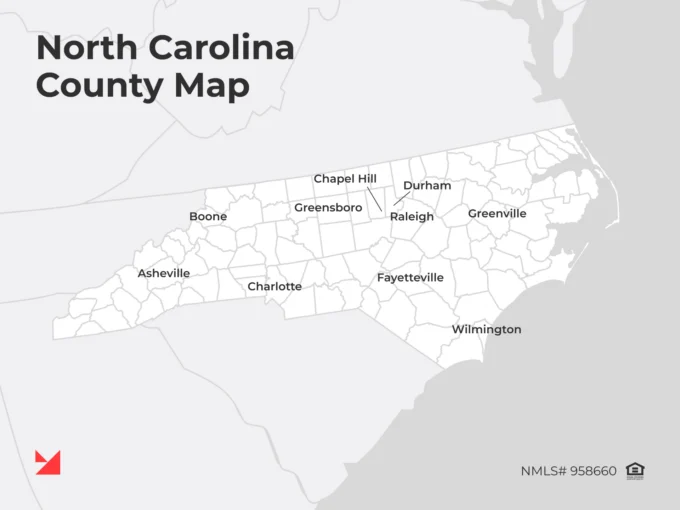
What It Costs to Buy and Own a Home in North Carolina
For many would-be owners, the hardest part comes before the first mortgage payment: gathering the cash to close the deal.
The tables below sort North Carolina counties into three entry-cost tiers. Estimated down payments are shown at 3% and 5% of typical home value, so buyers can size up what they might need to bring to the table. These figures exclude closing costs and other upfront expenses.
Price to Enter: Cost of Buying a Home in North Carolina
| County | Typical Home Value | Est. DP 3% | Est. DP 5% | What This Market Feels Like |
|---|---|---|---|---|
| Dare | $608,797 | $18,264 | $30,440 | Coastal market with premium pricing driven by vacation-home demand |
| Chatham | $571,137 | $17,134 | $28,557 | Fast-growing market attracting buyers seeking space near the Triangle |
| Currituck | $550,864 | $16,526 | $27,543 | Coastal suburban market offering larger homes with higher price points |
| County | Typical Home Value | Est. DP 3% | Est. DP 5% | What This Market Feels Like |
|---|---|---|---|---|
| Gates | $302,643 | $9,079 | $15,132 | Rural market offering affordability with a quieter lifestyle |
| Catawba | $299,277 | $8,978 | $14,964 | Established regional market with a mix of urban and suburban communities |
| Alamance | $298,620 | $8,959 | $14,931 | Mid-priced market benefiting from access to major employment hubs |
| Harnett | $298,259 | $8,948 | $14,913 | Expanding market attracting buyers looking beyond larger metro areas |
| County | Typical Home Value | Est. DP 3% | Est. DP 5% | What This Market Feels Like |
|---|---|---|---|---|
| Washington | $116,189 | $3,486 | $5,809 | Rural market offering low-cost entry for first-time buyers |
| Northampton | $114,032 | $3,421 | $5,702 | Budget-friendly market with affordable homeownership opportunities |
| Halifax | $104,082 | $3,122 | $5,204 | Lower-priced market providing strong value for cost-conscious buyers |
| Bertie | $62,232 | $1,867 | $3,112 | One of the state's most affordable markets for entry-level homeownership |
Cost to Hold: Ongoing Ownership Costs by County
The purchase price is only part of the affordability picture. After closing, property taxes and homeowners insurance arrive year after year, and they differ widely across North Carolina. A low price tag does not automatically mean a low cost of ownership.
We estimated the monthly cost of property taxes plus insurance, along with the share of home value that cost represents, and sorted counties into three burden tiers. The comparison tables are available in the Guide.
For example, Watauga, Jackson, and Transylvania counties form the low-burden group. Their estimated annual costs run from about $2,700 to $3,000, or roughly $225 to $250 a month, which works out to between 0.57% and 0.63% of home value. At the other end, Bladen, Robeson, and Bertie counties exceed 3.5% of home value.
Bertie illustrates the distinction: it is the least expensive county in the research and also posts the highest cost-to-value ratio, at about 6.4%. Its estimated annual cost of $3,963 is actually lower than Bladen’s or Robeson’s. The percentage runs high because the homes are priced so low, a reminder to read ratios and dollar amounts together.
Need help finding the right mortgage solution for your client? AD Mortgage offers a full range of loan programs, with experts available to help match borrower scenarios with appropriate financing options.
Where You Buy Shapes the Math
A listing is more than a number. Location decides the length of the commute, the distance to a hospital or grocery store, and the rhythm of an ordinary Tuesday as well as a free Saturday.
North Carolina packs three distinct landscapes into one state: the Blue Ridge Mountains in the west, the rolling Piedmont in the center where most of the big cities sit, and the coastal plain and Atlantic shoreline in the east. Each brings a different pace, a different job market, and a different price of admission.
First Takeaways
The county figures show how far apart North Carolina’s markets can be. Lower-priced homes tend to cluster in rural and inland counties, while coastal, mountain-resort, and Triangle-adjacent markets ask for considerably more. Taxes, insurance, and other recurring expenses can shift the picture, so a cheaper home is not always the cheaper one to own.
Down payment assistance adds another layer. Statewide options include the NC Home Advantage Mortgage and the NC 1st Home Advantage Down Payment, along with the Community Partners Loan Pool and the Self-Help Loan Pool for lower-income buyers. Several cities and counties run their own programs as well. Eligibility and availability depend on the buyer, the property, the loan type, the location, current funding, and program requirements.
With those factors in mind, we identified 10 cities that offer a compelling mix of home prices, ownership costs, job access, and available assistance.
Raleigh
Raleigh is the state capital and the state’s ambition in one place: a seat of government, a university anchor in NC State, and one corner of the Research Triangle, where technology, life sciences, and higher education keep the job market humming. The City of Oaks earns its nickname in leafy neighborhoods and a long network of greenways.
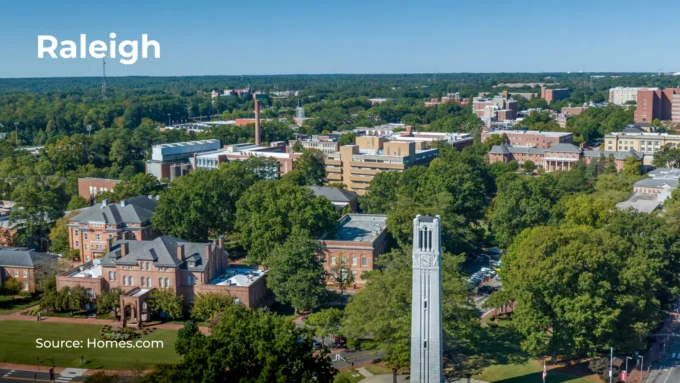
Downtown has filled in with restaurants, music venues, museums, and the nightlife of Glenwood South, while suburbs stretch out in every direction for buyers who want more space or newer construction. Raleigh suits people building careers who want a city that offers momentum without feeling rushed.
Raleigh is also one of the state’s deeper markets for assistance. Eligible first-time buyers may want to look at the Raleigh Homebuyer Program, which offers up to $45,000 in deferred, forgivable assistance, or up to $60,000 in designated areas, subject to program requirements.
Charlotte
Charlotte is North Carolina’s largest city and its financial engine, a skyline of bank towers rising over neighborhoods that keep reinventing themselves. Uptown supplies the corporate energy, South End brings converted-warehouse breweries and apartments, and NoDa leans into galleries and live music.
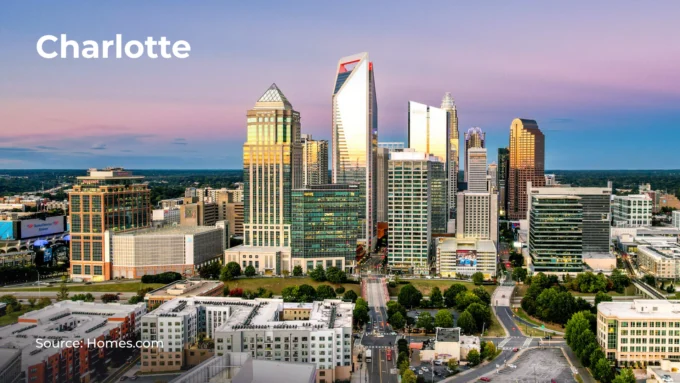
A major airport hub, professional sports, and a light-rail line give the city a big-market feel, while established neighborhoods, lake communities around Lake Norman, and growing suburbs give buyers real range. Commuters often look west to Gaston County, which our research places in the moderate-entry tier with a typical home value of $296,708.
For income-eligible first-time buyers, the HouseCharlotte Program offers up to $80,000 in forgivable assistance for homes in the City of Charlotte, subject to current requirements.
Durham
Durham has a swagger that comes from reinvention. Old tobacco warehouses now hold restaurants, offices, and event space, Duke University and its health system anchor the local economy, and the food and arts scenes of the Bull City draw visitors from across the region.
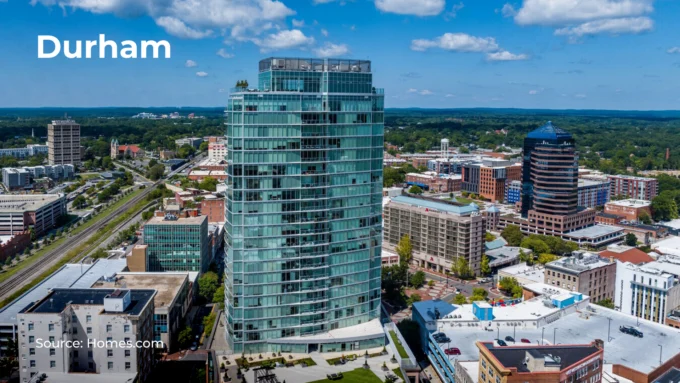
Research Triangle Park sits a short drive from downtown, which keeps a deep pool of employers close at hand. The result is a city that appeals to graduate students turned homeowners, health-care and technology professionals, and anyone who likes a city with a strong local identity.
Assistance is a real feature here. The Durham Down Payment Assistance Program offers up to $80,000 in deferred, forgivable loans for eligible first-time homebuyers within the City of Durham, subject to program terms and funding.
Greensboro
Greensboro is the largest city in the Piedmont Triad, and it wears its industrial and civic history openly. Textile mills built its early economy, the 1960 lunch-counter sit-ins secured its place in the story of the civil rights movement, and today universities, logistics, health care, and manufacturing keep the city moving.
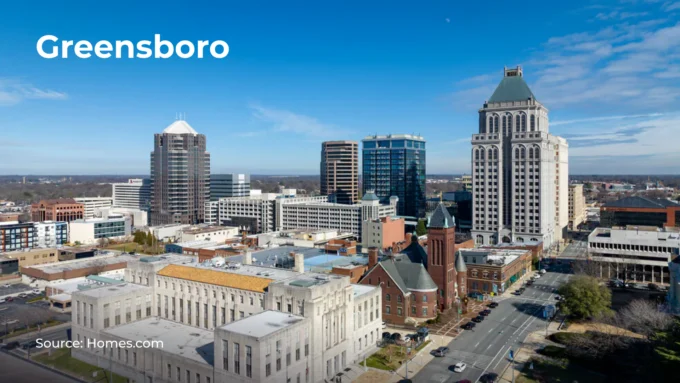
Weekends can mean a lap around Lake Brandt, a stroll through a redeveloped mill complex, or a game at one of the local campuses. In the research, Greensboro sits among the faster savings timelines, at just under eight years, a reflection of home values that are moderate relative to local incomes. Buyers casting a wider net can look east to Alamance County, where typical values run just under $300,000 and major employment hubs are within reach.
Two assistance options are worth a look. The Greensboro Homebuyer Assistance Program offers up to $25,000, plus up to $5,000 more in approved Redevelopment or Reinvestment Areas, for low- to moderate-income buyers and public service workers. Guilford County’s program offers up to $10,000 as a 0% deferred second mortgage forgiven over five years. Both are subject to eligibility and current funding.
Fayetteville
Fayetteville is a city shaped by service. One of the nation’s largest Army installations sits just outside town, and the military community influences the economy, the schools, the housing market, and the civic culture in ways that are easy to feel.
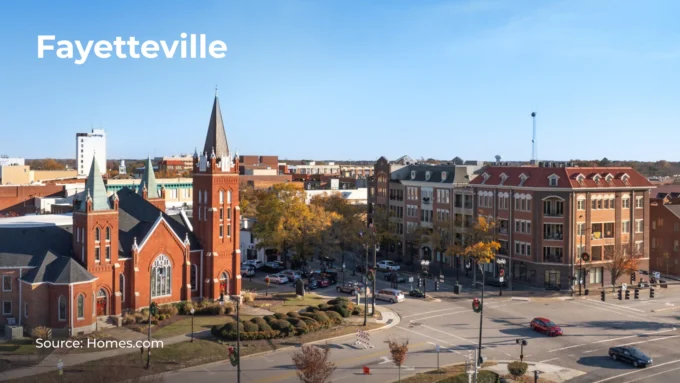
Downtown centers on the historic Market House, with the Cape Fear River, a botanical garden, and a museum devoted to airborne and special operations forces close by. Fayetteville also posts the shortest savings timeline of the 10 cities in the research, at just under eight years, making it a natural stop for buyers who want to move from renting to owning quickly. To the north, Harnett County appears in the research as an expanding market for buyers looking beyond larger metro areas.
The city’s Homebuying HERO Program offers up to $30,000 for income-qualified first-time homebuyers and local public service workers, subject to program requirements.
Wilmington
Wilmington splits its personality between the Cape Fear River and the Atlantic: a brick-lined historic downtown, a Riverwalk lined with restaurants and shops, and a short drive to Wrightsville, Carolina, and Kure beaches. A working port, a university, and a long-running film and television production scene add year-round activity beyond the tourist calendar.
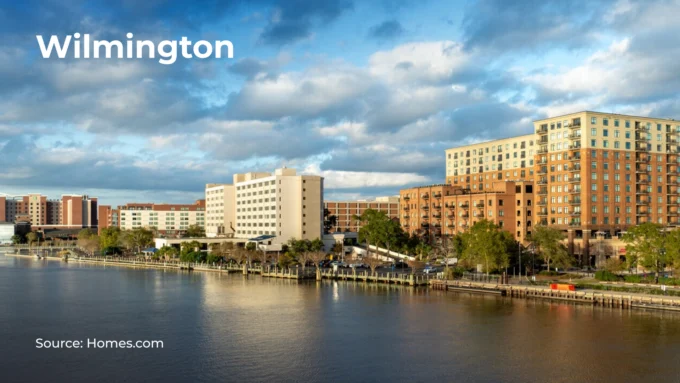
The tradeoff shows up in the numbers. Home values are high relative to local incomes, and the research places Wilmington’s savings timeline at more than 12 years, the third longest of the 10 cities. Coastal buyers should also budget carefully for insurance: Carteret County, farther up the coast, shows the highest insurance estimate in the ownership-cost tables.
For eligible low- to moderate-income buyers, the City of Wilmington’s Home Ownership Pool (HOP) offers up to $25,000 in assistance, subject to program requirements.
Chapel Hill
Chapel Hill is the academic heart of the Triangle. UNC-Chapel Hill, one of the nation’s oldest public universities, sets the calendar: Franklin Street on game days, Carolina blue everywhere, and a workforce of faculty, researchers, and health-care professionals that keeps demand steady.
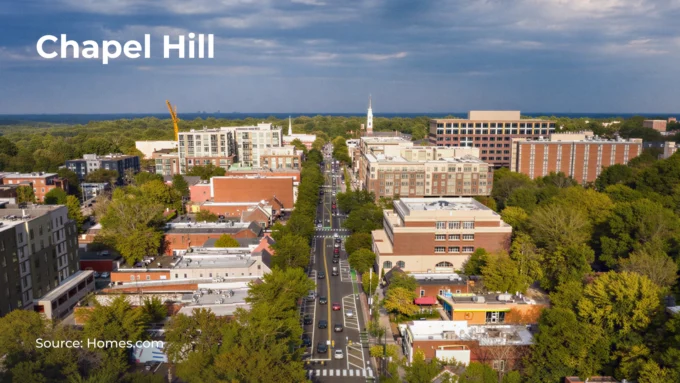
The town pairs walkable, tree-shaded neighborhoods with easy access to Durham and Raleigh, and it draws buyers who put a premium on schools and a college-town atmosphere. That premium is visible in the research: Chapel Hill has the highest typical home value of the 10 cities, at $642,319, and the second-longest savings timeline, at about 14 years. Just to the south, Chatham County appears as a fast-growing option for buyers seeking more space near the Triangle.
The research does not list a city-level program for Chapel Hill, but buyers may want to explore statewide options such as the Community Partners Loan Pool, which offers up to 25% (maximum $50,000) as a zero-interest subordinate loan for low- and moderate-income homebuyers, subject to eligibility.
Asheville
Asheville sits inside the Blue Ridge Mountains: an Art Deco downtown, studios and galleries in the River Arts District, a brewery scene that has become a regional calling card, and the Blue Ridge Parkway a short drive away. The nearby Biltmore Estate adds a touch of history to a place known mostly for its creative spirit.
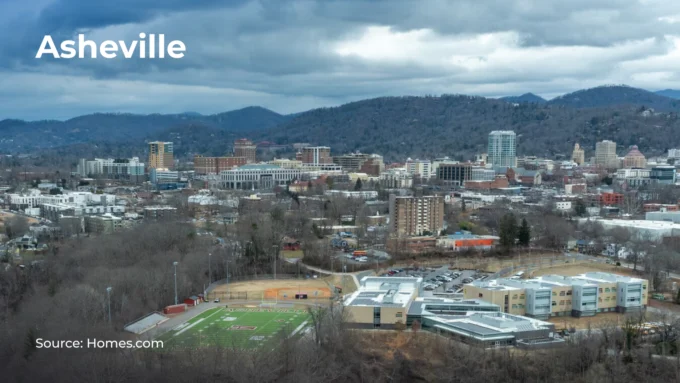
Remote workers, retirees, artists, and outdoor enthusiasts have all found their way here, and demand shows in the figures. With a typical home value of $464,131 against a median household income of $78,996, Asheville’s savings timeline runs about 11 years in the research. It is a market for buyers who want the mountains close and are prepared to plan for the cost.
Statewide assistance may help. The NC Home Advantage Mortgage offers up to 3% of the loan amount as a 0% deferred second mortgage. It is aimed at first-time and move-up buyers, subject to current program requirements.
Greenville
Not to be confused with its South Carolina namesake, Greenville, North Carolina, is the hub of the state’s eastern plain. East Carolina University and ECU Health make it a regional center for education and medicine, and its shops, restaurants, and services serve a wide surrounding area.
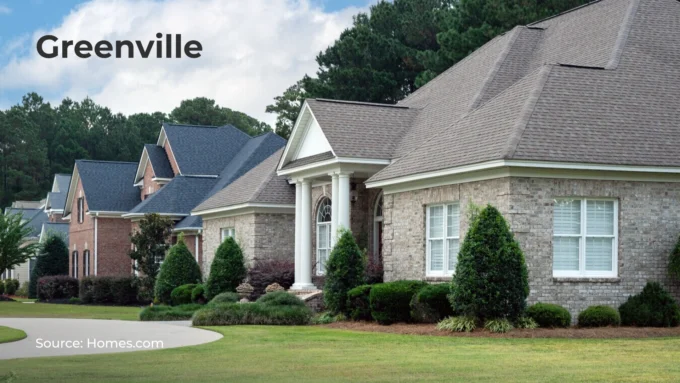
Uptown Greenville, the Tar River, and a lively Pirates game-day scene give the city a friendly, lived-in feel. With a typical home value of $238,644 and a median household income of $52,016, its estimated savings timeline of about 8.6 years is one of the shorter ones in the research, making it a practical option for buyers who want a college-town setting without a big-city price tag.
Buyers here may want to look at the statewide NC 1st Home Advantage Down Payment program, which offers up to $15,000 as a 0% deferred second mortgage forgiven over 15 years for first-time homebuyers or military veterans, subject to program requirements.
Boone
Boone sits more than 3,000 feet above sea level in the High Country, where Appalachian State University, the Blue Ridge Parkway, Grandfather Mountain, and nearby ski slopes shape a distinctly outdoor identity. King Street’s shops and cafes give the town a compact center, and the surrounding ridgelines are never far from view.
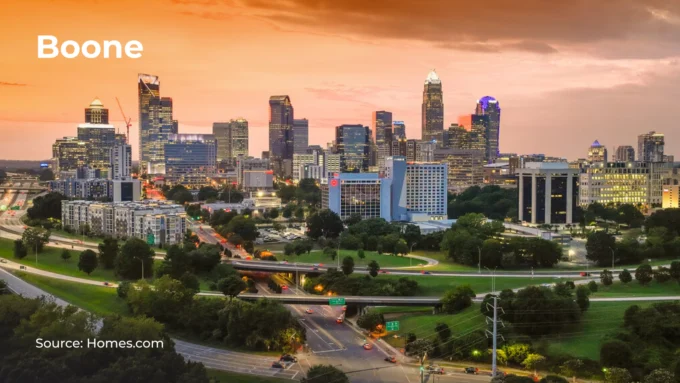
The numbers here are the most dramatic in the research. A typical home value of $494,937 stands against a median household income of $30,065, producing the longest estimated savings timeline of the 10 cities at roughly 31 years. Income figures in a university town can skew low because of the large student population, so buyers should look at Boone with that context in mind.
Ongoing costs tell a gentler story. Watauga County, which includes Boone, falls in the low-burden tier at about $245 a month for property taxes and insurance, and neighboring mountain counties Jackson and Transylvania join it. In other words, Boone is a steep climb to enter and a comfortable one to carry. Statewide programs such as NC 1st Home Advantage and the Community Partners Loan Pool are the places to start, subject to eligibility.
Choosing Your Corner of North Carolina
North Carolina is really three states in one: mountains, Piedmont, and coast. Each rewards a different kind of buyer, from the professional chasing opportunity in the Triangle or Charlotte, to the outdoor lover in the High Country, to the shopper for whom a low entry cost is the priority.
There is no single best place to buy. Lower home prices do not always mean lower long-term costs, as Bertie County shows, so buyers should weigh taxes, insurance, income, savings needs, and lifestyle alongside the purchase price. The right market depends on what matters most, whether that is job access, mountain views, ocean air, a shorter runway to ownership, or a monthly payment that stays comfortable.
For detailed market data, affordability comparisons, down payment assistance programs, and city-by-city figures, download the North Carolina Homebuyers Guide.
Thank you!
We’ll contact you as soon as possible
Oops, something went wrong
Please try to send form again