Hard Money Loans: How They Work, Costs, Risks, and Alternatives
·14 min read
Share Your Voice
Take Our Year-End Survey to Get 500 Loyalty Points and Exclusive Summary TAKE SURVEY
This article was originally posted on December 27, 2023.
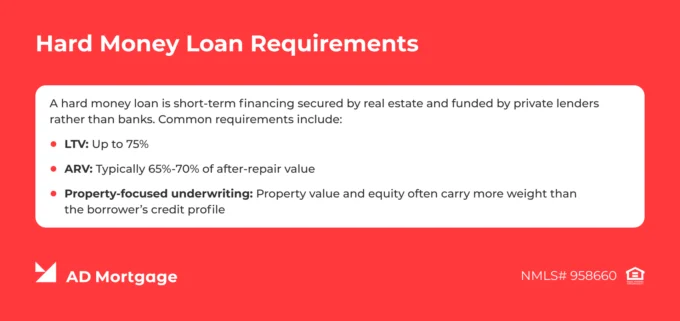
A hard money loan is short-term financing secured by real estate and funded by private lenders instead of banks. The lender underwrites the property and the plan to repay, so the money arrives fast.
Clients who ask, ‘What is a hard money loan?’ ‘ usually want that speed. It has a price – higher interest rates, upfront points, and short repayment periods.
The question on every deal is whether closing quickly is worth more than the added cost and repayment risk.
For informational purposes only. AD Mortgage does not currently offer this product.
What is a Hard Money Loan?
A hard money loan is an asset-based loan. Real estate secures the debt, and the property’s value drives the decision more than the borrower’s income or credit.
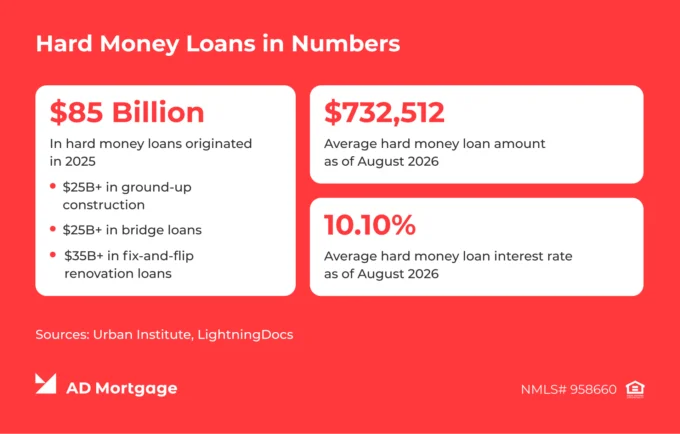
The Urban Institute describes hard money lending as private, asset-based, short-term, high-interest, business-purpose lending to real estate investors. The same report estimates that more than $85 billion in hard money loans were originated in 2025.
What is a hard money lender? Usually, private investors or specialized lending companies, as opposed to a traditional bank.
Unlike traditional mortgages, a hard money loan trades price for speed and comes with short repayment periods. It is an expensive way to borrow money, built for short holds. However, a hard money loan is not a bad-credit mortgage. Hard money real estate loans finance a deal: buy, improve, then sell or refinance.
How Do Hard Money Loans Work?
The lender determines the loan amount based on the property’s value and typically requires interest-only payments. Repayment terms are short, and the principal comes due in one balloon payment. These loans often have terms of 36 months or less.
On renovation loans, part of the financing may be released in draws as work reaches agreed milestones rather than paid out entirely at closing.
Asset-Based Underwriting
Traditional mortgages lean on income, debt-to-income ratios, and credit history. Hard money loans work the other way – the property comes first.
Underwriting places greater emphasis on the property and project than on the borrower’s personal income. Regulation Z generally exempts credit extended primarily for a business or commercial purpose, but that exemption does not determine a lender’s documentation requirements. Lenders still run a credit review and ask for a personal guaranty.
Loan-to-Value (LTV)
LTV divides the loan amount by the property’s current value. Lenders typically cap a hard money loan at 60% to 75% of value. Urban Institute research found the as-is ratio is usually no greater than 75% or 80%. A lower LTV puts more of the borrower’s cash into the deal.
After-Repair Value (ARV)
On a renovation, lenders consider ARV – the appraiser’s estimate of value once the work is done. The same research puts the usual ceiling at 65% to 70% of ARV. ARV explains why a hard money loan can fund a house no bank would lend on today.
Exit Strategy
Every hard money loan needs a clear exit strategy before closing:
Sell the finished property
Refinance into long-term debt
Stabilize the rents, then move into permanent financing
Without one, the balloon payment arrives with no way to pay it, and foreclosure risk follows.
‘We regularly refinance investors out of hard money loans, and the story is often the same: a short balloon deadline, a high rate, and a lot of stress about how to pay it off in time. Hard money has its place, but it should be a bridge, not the plan. When a borrower has a solid payment history on that loan, there’s often a path into longer-term financing with more manageable terms.’ – Brennen Moloney, SVP Business Development at AD Mortgage.
How Much Does a Hard Money Loan Cost?
Interest Rates
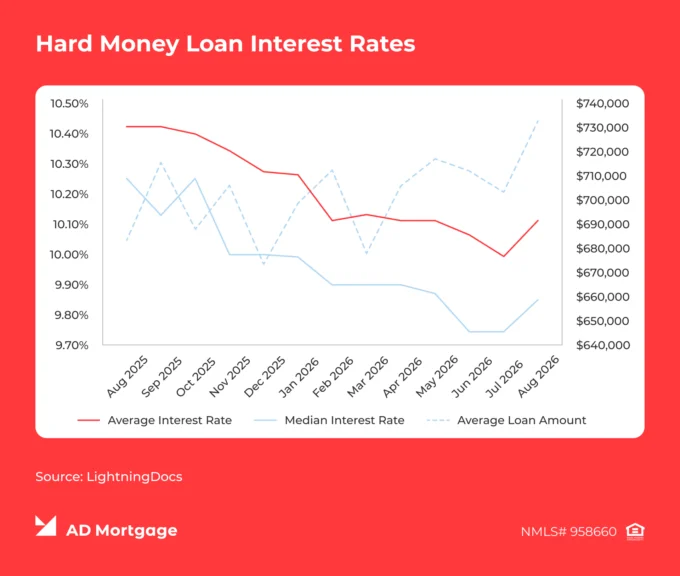
Lenders commonly quote hard money loan rates between 8% and 15%. Recent closings fall within a narrower range: 9.5% to 11.5% at the beginning of 2026, per the Urban Institute, and LightningDocs reported a 10.10% average in August 2026.
Compare that with traditional mortgages: Freddie Mac reported an average 30-year fixed mortgage rate of 7.40% as of Oct. 8, 2026. Lenders charge higher interest rates on a hard money loan because they take more risk and move faster. Interest rates change often, so date every quote you give a client.
Points and Origination Fees
Lenders typically charge 2% to 5% in origination points. The CFPB explains that one point equals 1% of the loan amount. For example, three points on a $300,000 loan would cost $9,000 at closing. Hard money loans usually carry higher upfront lender fees than Conventional loans, where origination fees are commonly around 0.5-1%.
Down Payment and Equity Requirements
A hard money loan usually requires a down payment of 20% to 40% of the purchase price. If the purchase price equals the lender’s accepted property value, financing 75% or 80% of that value leaves the borrower to fund the remaining 25% or 20% of the purchase price, plus applicable costs. Renovation funding and other underwriting limits can change the cash required. A riskier deal means a higher down payment. On a refinance, the home’s equity does the same job.
Other Potential Costs
Appraisal or property valuation
Closing costs: title, legal, and document fees
Extension fees if the project outlasts the loan term
Prepayment penalties on some loans
What are Hard Money Loans Used For?
Hard money loans work best on short investment timelines, where real estate investors need to move on time-sensitive opportunities.
‘Hard money solves a short-term problem, but high carrying costs and a looming balloon payment can hurt a deal when the timeline slips. For an eligible stabilized rental, DSCR financing can provide a longer-term strategy built around the property’s cash flow,’ comments Anna Veselenak, Account Executive at AD Mortgage.
Fix-and-Flip Properties
Fix-and-flip projects are the classic use. ATTOM counted 64,348 flips in the first quarter of 2026, and the typical flip took 165 days. However, 61.1% of these projects were funded with cash. A hard money loan can help your client compete with those cash buyers.
Investment and Rental Properties
An investor can use a hard money loan to purchase an investment property quickly, renovate and lease it, and then refinance into a long-term rental loan. The hard money loan carries the purchase, and a rental loan carries the hold.
Properties Requiring Major Renovation
Traditional lenders usually decline houses with no kitchen, failed systems, or structural damage. A hard money loan can finance an uninhabitable property because the lender prices the finished value.
Commercial Real Estate
Investors use a hard money loan to buy commercial property when traditional financing fails. Vacant retail, a mixed-use building, or a commercial property between tenants are common cases.
Bridge or Time-Sensitive Financing
Bridge loans cover a gap, such as buying before another property sells. Some homeowners facing foreclosure use bridge financing against their home’s equity to pay off a defaulted loan and buy time to sell. That is a costly last resort, so send the client to a housing counselor first.
Hard Money Loan Requirements: How Do You Qualify?
Hard money loan requirements vary considerably by lender. What do hard money lenders look for during underwriting? First and foremost, collateral. Most hard money lenders weigh the same items:
Property value, as-is and after repair
LTV and ARV limits
Borrower equity or down payment
Cash reserves for payments and overruns
Investment experience with similar projects
Renovation scope and budget
Exit strategy
Credit and income, which a lender may still review
On renovation loans, lenders evaluate experience, the construction budget, and liquid reserves, the Urban Institute found.
Paperwork is lighter than on a traditional loan: a purchase contract, a scope of work, entity documents, and proof of funds. This can result in faster approval and fewer documentation requirements than traditional mortgage financing. Hard money lenders may also offer more flexible qualification standards.
Hard Money Loan vs Traditional Mortgage
Traditional mortgages reward a strong borrower with lower rates and long repayment terms. A hard money loan rewards a strong deal with speed.
Hard Money Loan vs Traditional Mortgage
Factor
Hard Money Loan
Traditional Mortgage
Primary Underwriting Focus
Property/deal
Borrower finances
Typical Lender
Private/specialty lender
Bank/mortgage lender
Funding Speed
Faster
Longer underwriting
Loan Term
Short-term
Long-term
Interest Cost
Generally higher
Generally lower
Down Payment/Equity
Generally higher
Usually lower
Primary Use
Investment/short-term projects
Homeownership/long-term financing
A hard money loan can close in 5 to 15 business days, and some fund in a week or less. A bank construction loan takes 45 to 60 days, per the same research.
Short-term loans like these trade cost for time. Traditional mortgages spread repayment over decades, while a hard money loan has short repayment periods measured in months.
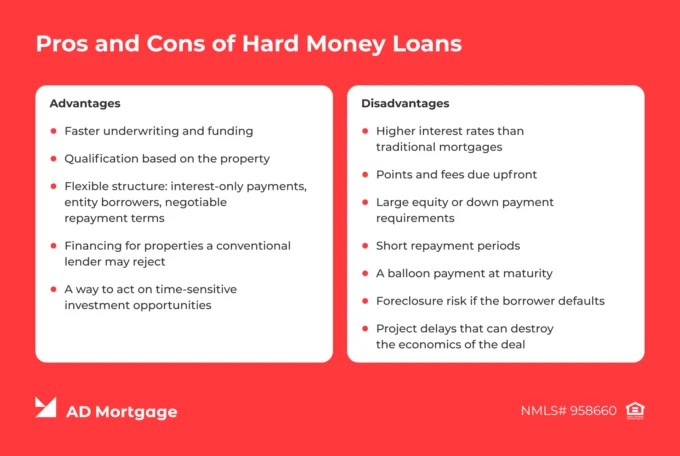
Financing for properties a conventional lender may reject
A way to act on time-sensitive investment opportunities
Disadvantages
Higher interest rates than traditional mortgages
Points and fees due upfront
Large equity or down payment requirements
Short repayment periods
A balloon payment at maturity
Foreclosure risk if the borrower defaults
Project delays that can destroy the economics of the deal
On that last point, ATTOM put the typical gross flipping return at 25.4% before rehab and other expenses in early 2026. Every extra month of higher interest rates and extension fees comes out of that margin, and the repayment terms on a hard money loan leave little room for a slow contractor.
When Does a Hard Money Loan Make Sense?
A hard money loan makes sense when speed creates more value than the loan costs. Most hard money loans that end well share a profile:
A competitive or time-sensitive purchase
A fix-and-flip with a defined timeline
A distressed property that traditional financing will not cover
A renovation before refinancing
An investor with a calculated margin and an exit strategy
For clients like these, short-term loans are part of the business model. They borrow money, finish the work, and repay.
Before your client takes a hard money loan, document the expected sale price, project timeline, and backup repayment plan. If refinancing is the exit, confirm the likely program’s property, credit, reserve, and documentation requirements before closing.
When Should You Avoid a Hard Money Loan?
A hard money loan is a short-term solution. It is generally unsuitable for long-term financing or purchasing a primary residence because its higher interest rates make it expensive to carry over several years.
Steer clients away when:
They plan to hold the property long term
It is a primary residence and a traditional loan is available
The renovation or profit margin is thin
The resale timeline is uncertain
No reliable refinance path exists
Cash reserves cannot absorb delays
Traditional mortgages cost less over time, so a client who qualifies for one should start there. If a client’s financial situation cannot survive a delay, it cannot support a hard money loan.
‘Hard money can get an investor into a deal fast, but the clock starts the day it closes. A few months of permit or contractor delays can mean extension fees, more months at a double-digit rate, and a balloon payment coming due before the property is ready to sell or refinance. Those costs come straight out of the flip profit. That’s why the exit strategy has to be planned before closing, not after the project runs long.’ – Brennen Moloney, SVP Business Development at AD Mortgage.
Alternatives to Hard Money Loans
Hard money solves a specific problem, but not every nontraditional scenario requires hard money. AD Mortgage does not offer hard money loans. As a wholesale lender operating coast to coast, we cover the longer-term side through our mortgage programs.
DSCR Loans
A DSCR loan qualifies a rental on the property’s cash flow, with no personal income or employment documentation. According to LightningDocs, DSCR rates stood at 7.18% in August 2026, almost three percentage points below the hard money loan average in the same data. AD Mortgage’s program starts at a 620 FICO and goes up to 80% CLTV.
A client with significant equity can take a second mortgage against the home’s equity and keep a low first-lien rate. AD Mortgage lends up to $500,000 at up to 90% CLTV. Banks and credit unions offer a home equity loan or a home equity line of credit. A home equity loan pays a lump sum, and a home equity line works like a revolving account.
Cash-Out Refinance
A cash-out refinance replaces the current mortgage with a larger one and turns existing equity into cash. A cash-out refinance works when the new rate and costs beat a second lien on the home’s equity. Compare the total borrowing cost over the expected holding period, including the effect of replacing the existing first-mortgage rate.
Bank Statement / Other Non-QM Loans
When income documentation, rather than the property itself, is the obstacle, a bank statement mortgage or another Non-QM loan option may be a better fit. Our Non-QM loan guidelines show how to match them. For a small rehab, a personal loan or small business line of credit may be enough.
Hard money loan terms differ widely among private lenders, and a hard money loan from the wrong lender can sink a good deal. Have your client check these before signing:
Licensing required in the property’s state. NMLS Consumer Access shows a lender’s licenses
Interest rates and how the lender calculates them
Points
Total closing costs
Maximum LTV and ARV
Extension fees
Prepayment penalties
Funding timeline
Repayment terms and default provisions
Experience with the property and project type
Ask each lender for a written term sheet, then compare every hard money loan offer side by side. We do not recommend specific hard money lenders.
Final Thoughts
The key takeaways are simple. Speed and flexible, property-based underwriting are the primary benefits of a hard money loan. Higher costs and repayment risks are the tradeoffs.
Help your client close the loan quickly only when the numbers still work after interest rates, points, and delays. When the plan is to hold the property, evaluate a longer-term financing option and confirm the refinance requirements early. Submit a scenario and an AD Mortgage Account Executive will contact you within 30 minutes.
Usually not, if the deal is sound. A hard money loan depends on equity, a realistic budget, and a credible exit. A weak property is harder to finance than weak credit.
Do hard money lenders check credit?
Most do. Urban Institute research found lenders typically run a soft credit pull on the guarantor. They focus more on defaults and bankruptcies than on a specific credit score.
What credit score is needed for a hard money loan?
No universal minimum exists. Each lender sets its own floor, and equity or experience can offset a lower score. Ask for the hard money loan requirements in writing.
What is a hard money loan example?
An investor buys a $200,000 house using a $150,000 hard money loan and $50,000 in cash, then funds $40,000 in repairs. If the house sells for $300,000 six months later, the investor uses the proceeds to repay the loan. Any profit depends on interest, lender fees, holding costs, and selling expenses.
How quickly can a hard money loan close?
Many close in 5 to 15 business days, and some in a week or less. Appraisal access and title work set the pace. Traditional mortgages take longer because the borrower’s full file needs review.
What happens if you cannot repay a hard money loan?
The lender may extend the hard money loan for a fee. Otherwise it can foreclose and take the property. The CFPB warns that failing to pay a balloon payment can end in foreclosure.